
RB Wheelz is RenewBuy’s dedicated auto loan platform launched in April 2025 to simplify vehicle financing across India. The platform offers a comprehensive suite of loan products, including new vehicle financing, balance transfers, and top-up loans, refinancing combined with insurance solutions in one place. RB Wheelz operates through a digital-first approach supported by partnerships with 18+ leading banks and NBFCs, enabling streamlined loan processing with faster approvals and less paperwork.
RB Wheelz targets both metropolitan and smaller urban areas, with a particular focus on Tier II and III cities where over 80% of consumers opt for vehicle financing. The platform use RenewBuy’s network of 1.5 Lakh+ advisors to extend accessibility to reserved markets.
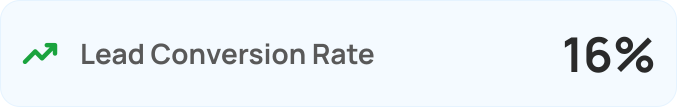
After RB Wheelz launched in April 2025, 1.25 lakh+ RenewBuy advisors could sell new vehicle loans. However, lead-to-disbursement conversion was only 6–8%, which was too low given high lead costs and advisor effort.
After capturing a new lead, we must check eligibility and loan amount with banks and NBFCs. This process is manual and time-consuming for the operations team. As a result, rejection rates are high from both lenders and customers.
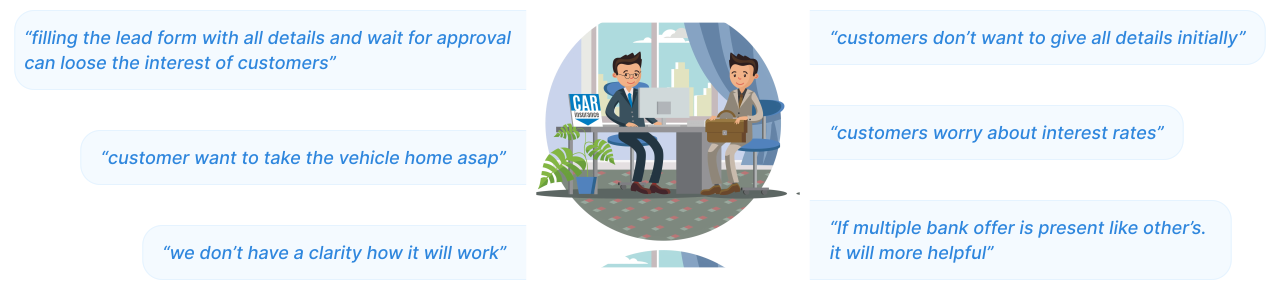
We conducted a few interviews with rejected loan applicants and with our FLS partners. I led the planning, interviews, and recorded the feedback. Customers cancelled loan applications mainly due to slow eligibility checks, a lack of multiple options, high interest rates, and low transparency. Most lender rejections applications due to low credit scores and ineligibility for the desired loan amount.
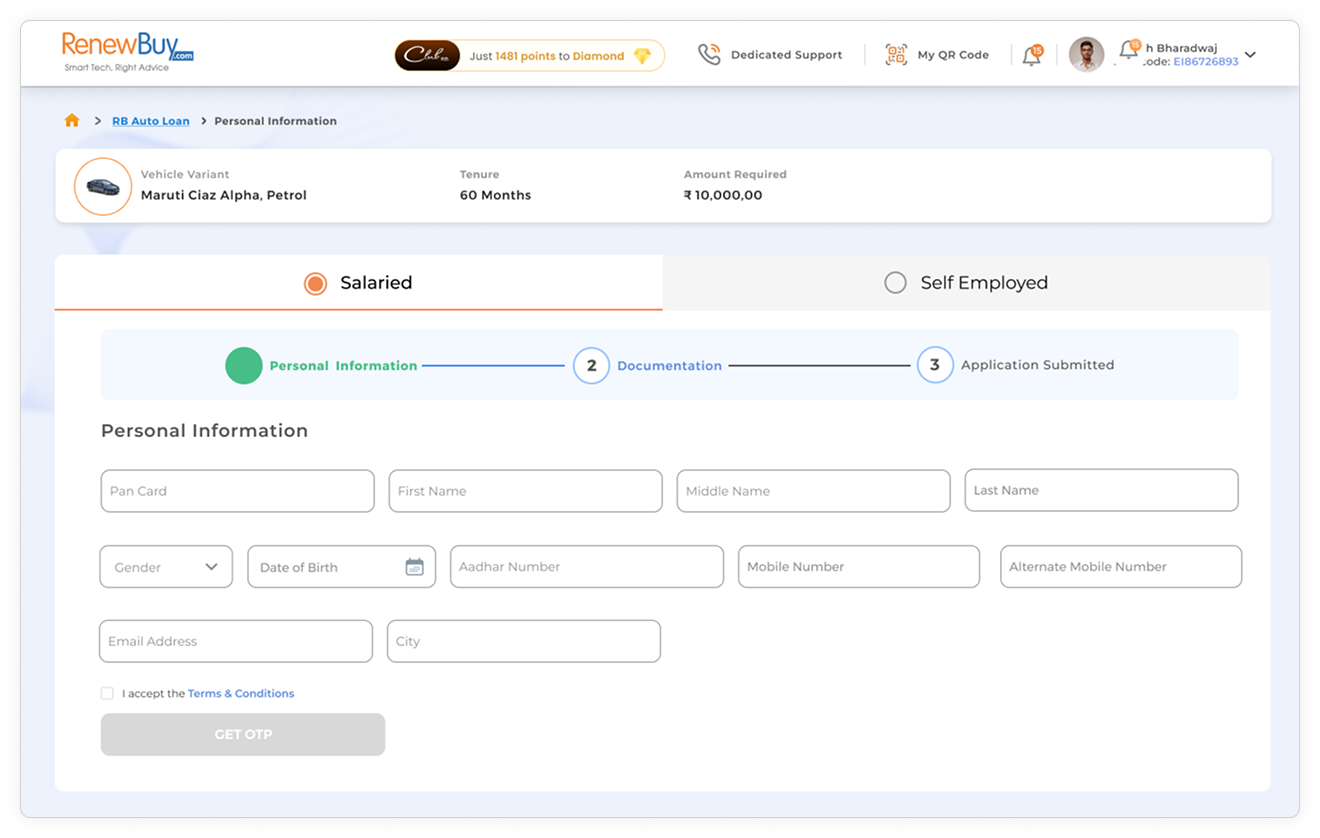
If advisors want to capture a loan lead, they must complete the full lead form like desired loan amount, personal and professional details and upload all required documents to portal. Our DST team then runs eligibility checks across multiple banks and responds to the customer. This end‑to‑end flow is time‑consuming and requires significant effort for every new lead.
we started with how might we statement. We focused on the following questions to be addressed as part of our work.
I created user stories for this initiative and identified what information our partners needed and what customer.
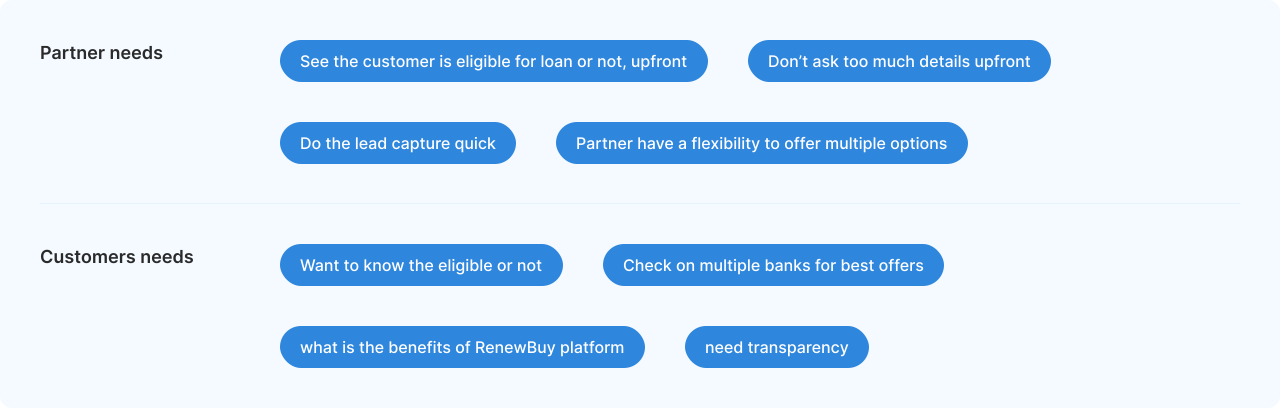
We collated all the research findings, gained insights, did some brainstorming with stakeholders, paper sketching and started to design for this problem. Tried out many iterations and designed the solutions for this problem statement. There were three major solutions that helped to solve this problem:
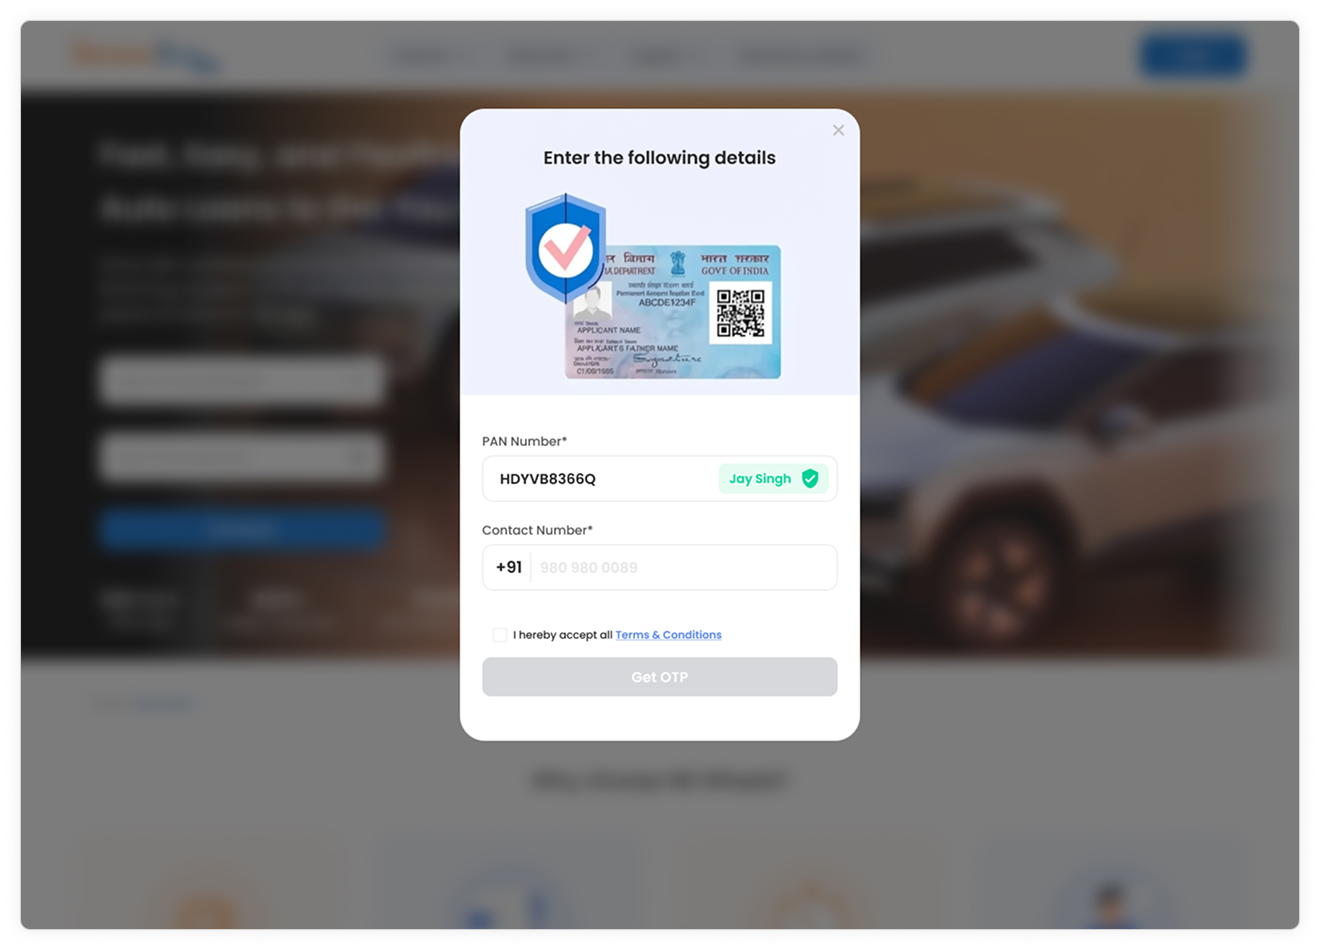
To capture new leads, now advisor first verify customers’ credit eligibility using PAN verification and a credit check. This quick screening takes 3–5 minutes and filters out qualified leads. If a customer is eligible for the loan amount and has a good credit score, they are marked as qualified and proceed to the second screen. Customers who do not meet the eligibility criteria must complete a longer form and await approval from the DST team.
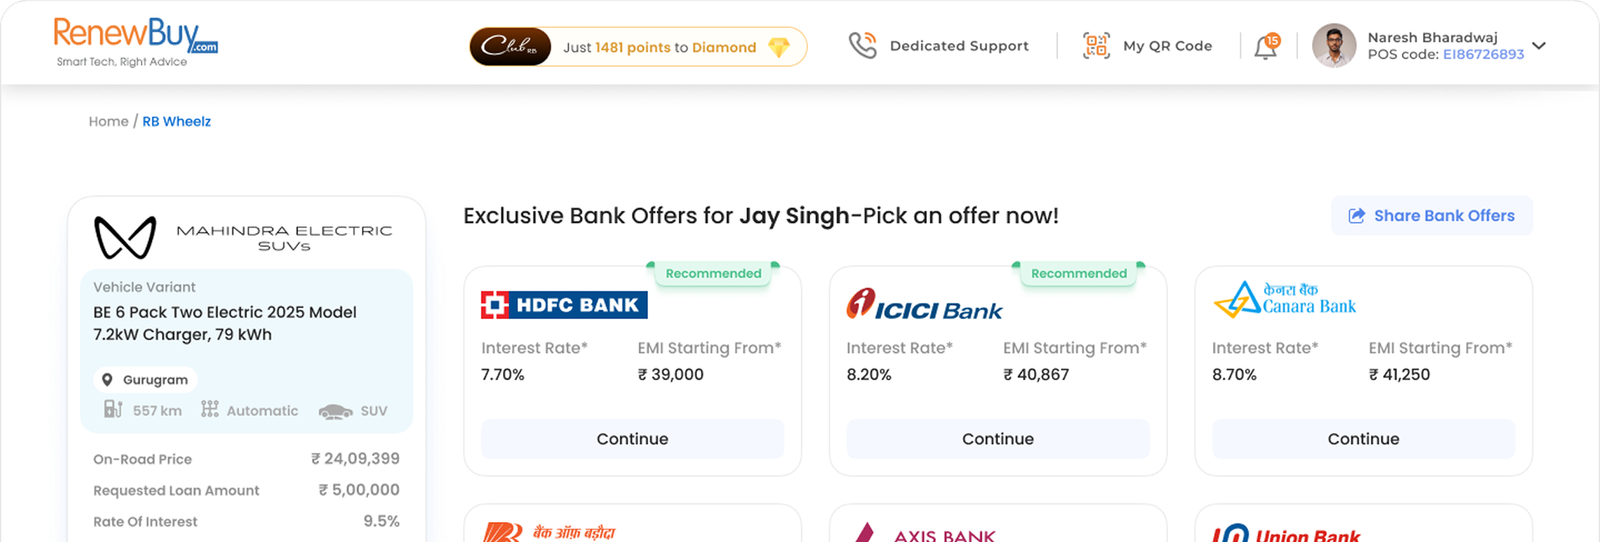
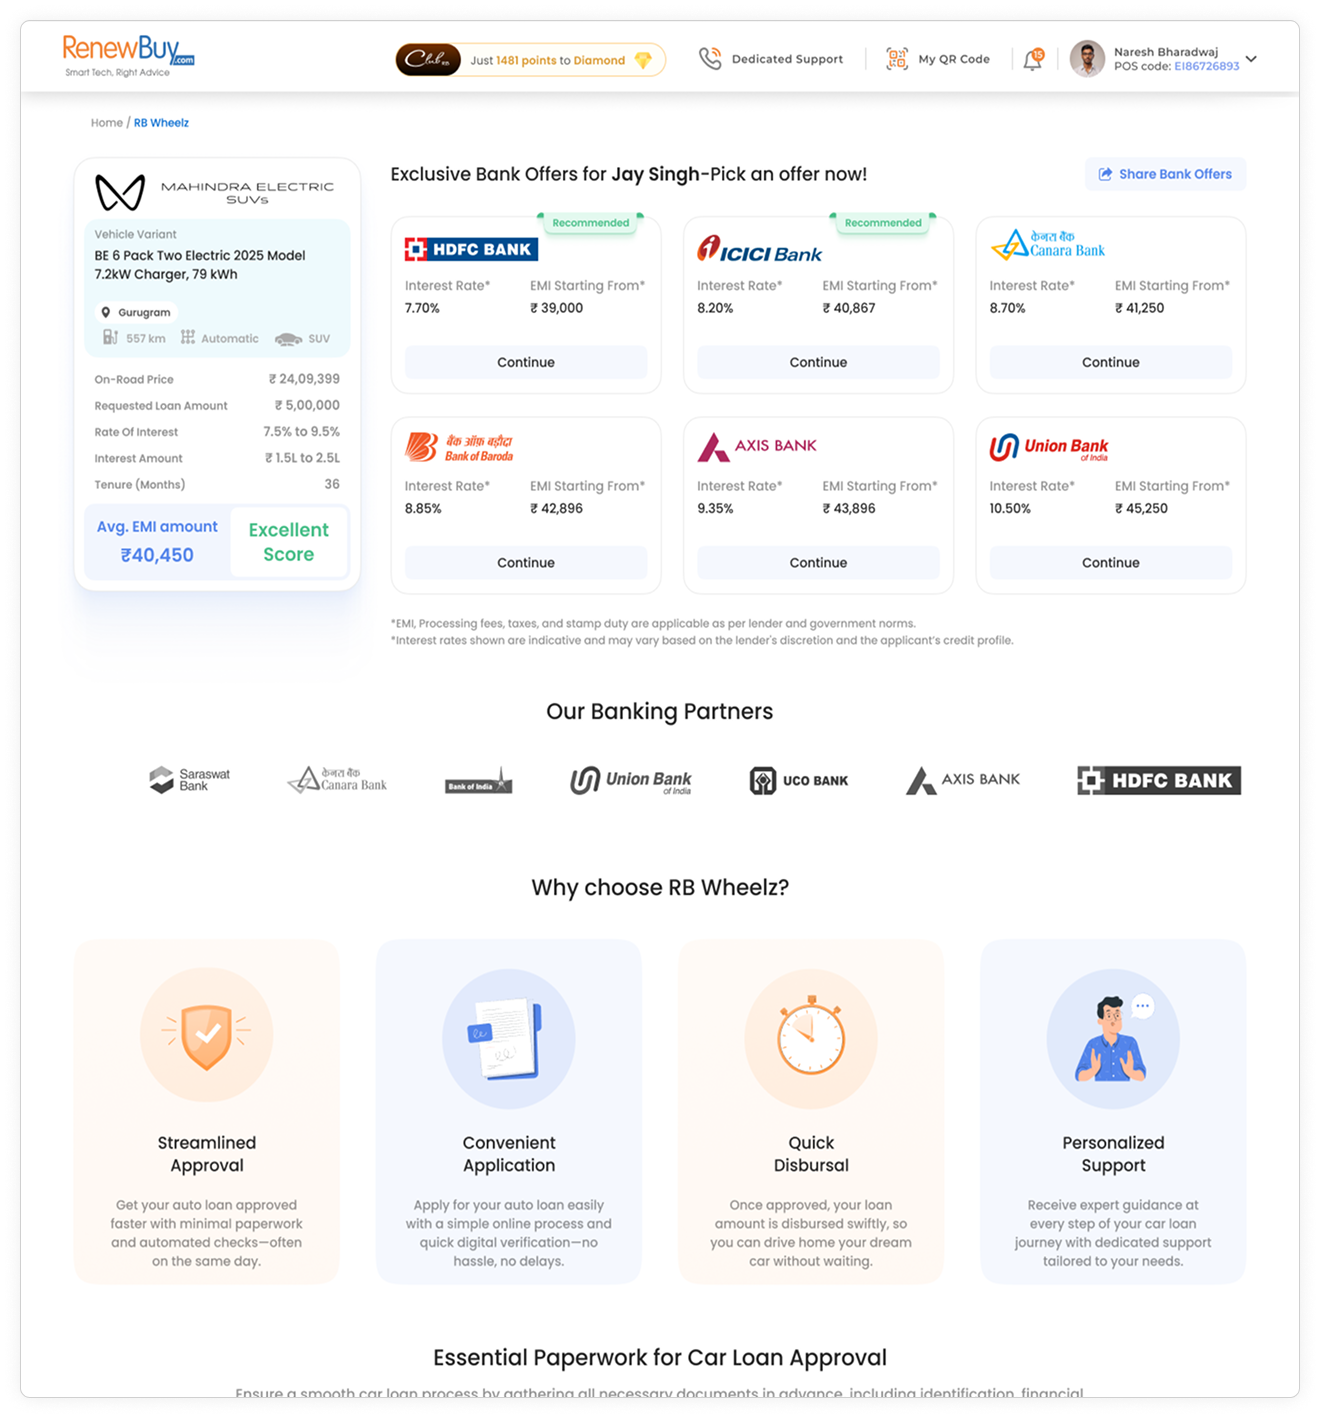
After the initial screening, if the customer is eligible and has a good credit score, the system shows multiple bank offers on the advisor’s dashboard. Each offer displays the eligible amount, interest rate, and monthly EMI. Advisor can now share these offers with the customer directly, which improves transparency and lets the customer choose their preferred bank and offer.
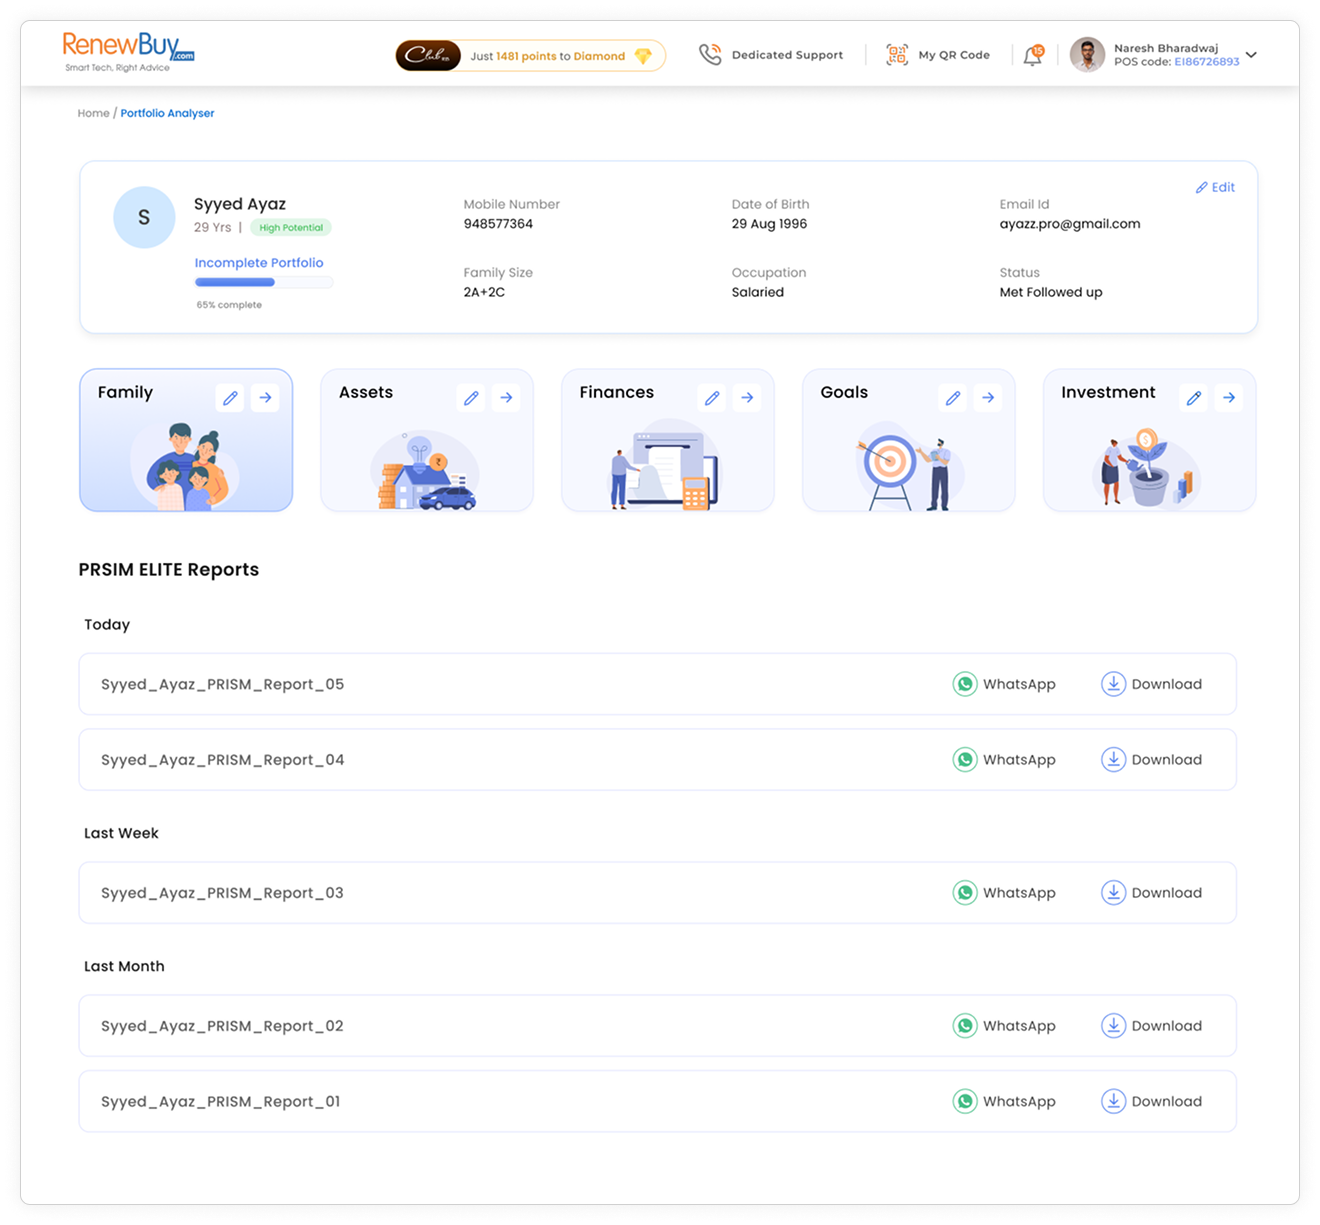
This feature is for FLS Partners with existing customer lists from insurance or loans. FLS Partners or advisors can shortlist customer profiles based on current credit eligibility, then proactively offer relevant products like top-up loans, balance transfers, or refinancing. This turns dormant portfolios into qualified, low‑cost leads and improves conversion.
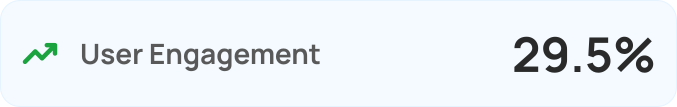
After UAT testing with advisors and several final iterations, we rolled the feature out to production for all FLS Partners and advisors across India. After advisors training’s with over a three‑month period, we observed measurable improvements: higher lead engagement and more meaningful conversations, a reduction in loan rejections due to poor credit, and increased daily efficiency for both advisors and the DST team.
Some of the information, visuals, and details presented in this case study have been modified, simplified, or generalized to respect confidentiality and protect the privacy of company projects. The case studies and examples are intended solely to showcase my design process, skills, and approach, without disclosing any sensitive or proprietary business information.